A customer slips
Injury to the public
Someone is hurt at your premises, or because of your work. Public liability responds to claims like that, on the terms of the PDS.
A customer slips, a job damages a client’s property, something you sold goes wrong. Public liability is the core of Gary’s business pack: quote it on its own at the limit your lease or contract asks for, or add property, stock and theft in the same form. A real broker places the policy.
Public liability is about accidents involving other people and their property. A client’s money, lost to your advice, is a different policy: public liability vs professional indemnity.
Injury to the public
Someone is hurt at your premises, or because of your work. Public liability responds to claims like that, on the terms of the PDS.
Your premises
An office counts as much as a shop. Clients, couriers and visitors are all members of the public.
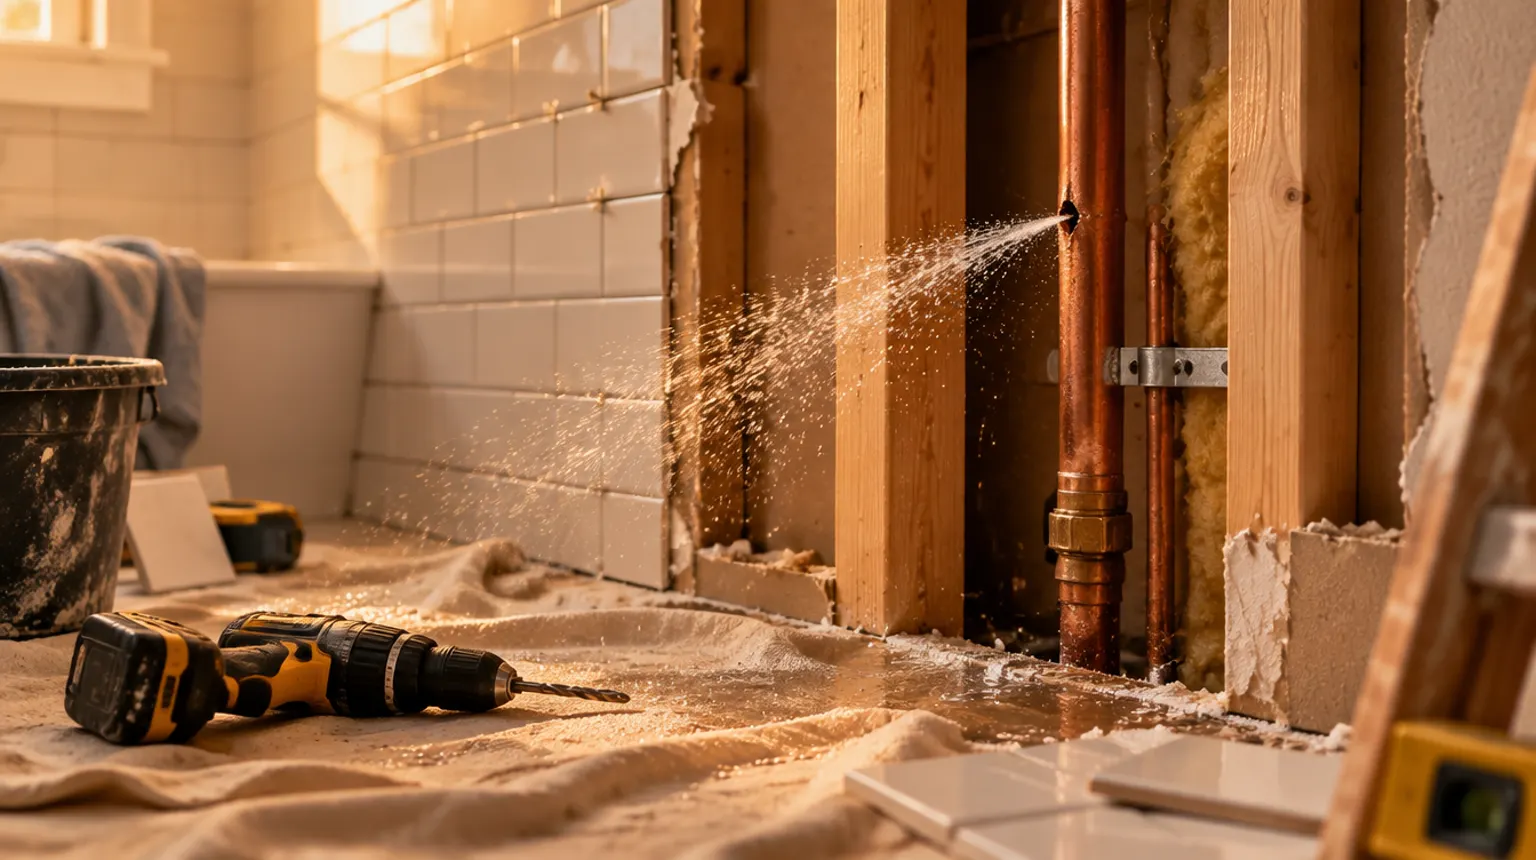
Damage to other people’s property
Your work damages someone else’s property, like a drilled pipe or a scorched benchtop. Fixing your own work is a different matter.
Products liability
Injury or damage caused by something you sold, supplied or installed, after it has left your hands. Most packs include it beside public liability.
Legal defence costs
Defending a claim costs money even when you’ve done nothing wrong. Defence costs are generally paid on top of the claim itself, within the policy’s terms.
Property, theft, interruption & more
Switch on the other sections of the business pack in the same form, and it’s one policy.
See business insuranceTest yourself · 4 minutes
Public liability wordings are written around injury and damage to other people. These sit with other policies, or with none, and knowing which saves a phone call after the fact.
You pick your business from the full list of Australian industry codes. Each insurer decides which it writes, and the quote says so plainly when one won’t.
Guides for some of them: plumber insurance, electrician insurance, personal trainer insurance, market stall insurance and sole trader insurance.
Your business, where you work and your turnover. Liability is in the pack from the start; switch on property, stock or theft only if you need them.
Each one rates the same answers, and every quote names its insurer and links its PDS.
You pick and pay; a broker places the policy and your certificate of currency arrives by email.
Liability only? Leave the other sections switched off.
Insurance for the compensation you become legally liable to pay when someone outside your business is injured, or their property is damaged, in connection with your business. It generally also pays the legal costs of defending a claim like that.
Yes. Public liability is the standard section of the business pack, and every other section is one you switch on. Leave them off and the quote is for liability alone. You can switch more on later.
It depends on your business and your contracts. Landlords, councils, venues and head contractors often set a minimum in the lease or contract, commonly $10 million or $20 million. The form offers limits from $5 million to $20 million, depending on the insurer. A higher limit costs less extra than people expect: when we priced the same businesses at each limit, $20 million cost 24% to 100% more than $5 million with the same insurer.
No. Injury to your own staff is workers compensation, which employers must hold under state and territory law, and public liability wordings exclude it.
Generally not. Public liability wordings exclude professional advice or service. A claim that your advice or design cost a client money is what professional indemnity is for.
A one-page document from the insurer confirming the policy is in force, its limit and its dates. Landlords and head contractors usually ask for one before you start. Your broker sends it with your policy documents.
Everything here is general information only. It doesn’t consider your objectives, financial situation or needs. We explain how public liability works and show what businesses like yours commonly choose; read the PDS and decide what fits.
What each limit costs in real prices: $5 million vs $10 million vs $20 million public liability.
Guide
Real prices our insurers returned, by business, limit and turnover.
Read onGuide
When you are the business: who asks for it, what it costs, what it skips.
Read onGuide
Victoria’s licence rule, the clauses that matter to plumbers, and real prices.
Read onGuide
The proof your lender, landlord or head contractor asks for, and how to get it.
Read onPublic liability comes in the business pack, with property, stock and theft there to switch on. Every quote names its insurer, links its PDS, and shows what the premium includes and how we’re paid, in writing rather than in the fine print.